The short answer
- Which? advises a guarantee of at least 10 years. TrustMark expects its registered businesses to give at least two years.
- An insurance-backed guarantee (IBG) only steps in if the installer stops trading, and it can be shorter than the written guarantee. Guardian's covers workmanship issues arising in the first two years.
- Deposit protection typically covers up to 25% of the contract value for about 120 days. DGCOS caps it at £5,000, CPA at £7,500 and HomePro at £10,000.
- Paying by credit card adds Section 75 protection on items costing over £100 and up to £30,000, even if only the deposit went on the card.
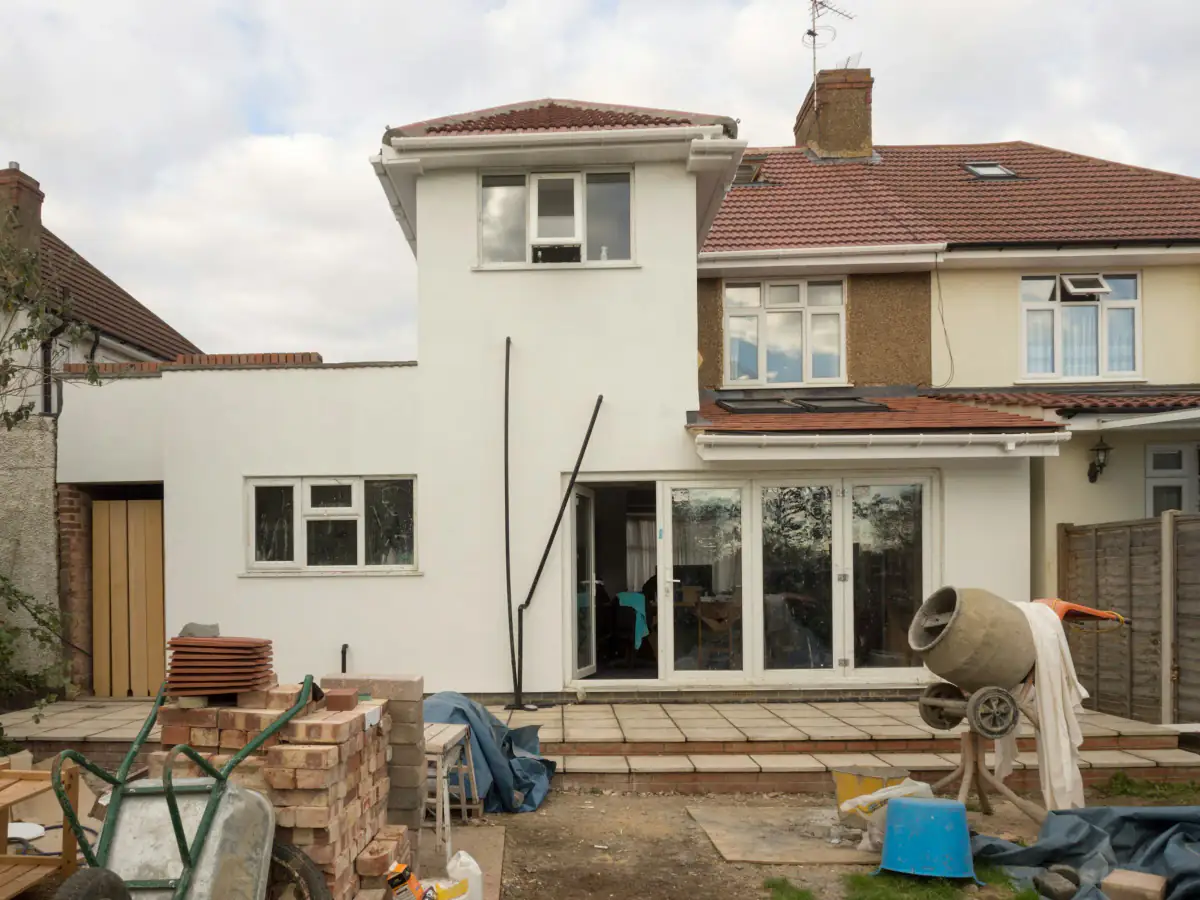
A new conservatory roof should come with a product guarantee from the company that makes the roof system and a workmanship guarantee from the firm that fits it. Which? advises that any guarantee should last at least 10 years. The weak point is not the length but who stands behind it: a workmanship guarantee from an installer that has closed down is worth nothing unless it is insurance-backed.
This guide explains the four kinds of protection, what the main roof makers and installers publish, and how to check them before you sign.
What guarantee should a new conservatory roof come with?
Expect a product guarantee from the roof system maker and a separate workmanship guarantee from the installer, each lasting at least 10 years, which is what Which? advises. Ask for an insurance-backed guarantee as well, so the workmanship cover survives if the installer stops trading, and for deposit protection that lasts until the job is finished.
TrustMark sets a lower floor: its registered businesses are expected to give a guarantee of at least two years covering workmanship, defects and building regulations non-compliance.
Four kinds of protection, and what each covers
These are often bundled together in sales talk, but they protect different things at different times.
| Protection | Who gives it | What it covers | What it does not cover |
|---|---|---|---|
| Product guarantee | The roof system or tile maker | Faulty components | Poor fitting, unless the terms say so |
| Workmanship guarantee | The installer | Installation defects | Anything, once the installer has stopped trading |
| Insurance-backed guarantee (IBG) | An insurer, arranged by the installer | Honours the installer’s guarantee if it ceases trading | Deposits; and often a shorter period than the written guarantee |
| Deposit protection | An insurer or scheme | Your deposit, if the firm fails before finishing | Incomplete work beyond the deposit; deposits above the limit |
One installer puts the last point plainly: deposit protection “only insures your deposit”.
What roof makers and installers publish
These are the companies’ own statements as reported in September 2026. Terms change, so ask for the current document.
| Company | What it says it offers |
|---|---|
| Guardian Warm Roof | 10-year product guarantee and 10-year workmanship guarantee from its Certified Installer. The insurance-backed guarantee covers workmanship issues arising within two years of completion if the installer ceases trading. Applies only to roofs fitted by Guardian Certified Installers. ExpertSure reports a 25-year tile warranty |
| Ultraframe LivinRoof and Ultraroof | 10-year parts guarantee; installer warranties vary. ExpertSure reports the LivinRoof guarantee is not insurance-backed |
| Leka | 40-year component warranty and 40-year tile warranty, excluding products in the roof that Leka did not supply |
| Eurocell Equinox | Roof guaranteed for 10 years; tiles up to 40 years depending on type (25 years for SlateSkin and Envirotile). ExpertSure says the system guarantee is dealer-administered, not insurance-backed |
| SupaLite | 10-year guarantee on its product page; Tapco Slate tiles carry a 10-year tile guarantee as standard. ExpertSure says the full warranty terms are not published |
| Warmer Roof | 25-year manufacturing warranty and 40-year tile warranty; the installer’s workmanship cover is separate |
| Metrotile and Britmet tiles | Metrotile: 40-year weatherproof warranty. Britmet: 50-year guarantee |
| Anglian | 10-year guarantee on conservatories and its Solaroof glass, 15 years on sealed units |
| Everest | 10-year guarantee including discolouration of uPVC and leaks |
| Green Space panels | 10-year panel guarantee and 1-year workmanship warranty |
| Internal insulated ceiling firms | Mostly 10 years; one firm offers 5 years as standard |
Two things to read into this. A long tile or component warranty is not a long guarantee on the whole roof, and one solid-roof installer argues that panel guarantees often cover “only the panels themselves”. And the Guardian terms above come from its consumer promise; another Guardian-branded site advertises a “10 Year Insurance Backed Guarantee”, so check which terms apply to your roof. See our Guardian Warm Roof review and Leka review for more on each system.
What is an insurance-backed guarantee?
An IBG is an insurance policy that honours the installer’s written guarantee if the business ceases trading. HomePro describes IBGs as issued by FCA-regulated providers and underwritten by regulated insurers. Providers include HomePro, QANW (policies up to 10 years), the Consumer Protection Association and DGCOS (IBGs of 2 to 10 years).
The catch is length. DGCOS warns an IBG may be shorter than the installer’s own written guarantee, and Guardian’s covers workmanship issues arising in the first two years, against a 10-year workmanship guarantee from the installer. Ask for the IBG certificate in your name, check the start date and length, and keep it with your roof paperwork.
Installer failure is not a remote risk in this trade. Companies House shows administrations or liquidations at Synseal (2019), Everest (2020 and 2024), Safestyle’s trading company (2023) and Prefix Systems (2025), among others. When Everest’s 2020 successor company declined to honour earlier customers’ guarantees, BBC Watchdog criticised it. Reviewers of Guardian roofs report certified installers ceasing trading and leaving customers without recourse.
How deposit protection works
Deposit protection insures the money you pay upfront if the installer fails before the job is finished. The main schemes publish these limits:
| Scheme | Cover | How long |
|---|---|---|
| DGCOS | Up to 25% of contract value, maximum £5,000 | 120 days from signing; active once DGCOS confirms cover in writing |
| Consumer Protection Association | Up to 25% of project costs or £7,500, whichever is lower | Up to 120 days or until work begins |
| HomePro | Deposits up to 25%, maximum £10,000 | Not stated in our research |
| QANW | Not stated in our research | Generally 120 days from paying the deposit |
DGCOS says its cover does not extend to deposits or stage payments above 25% of the contract value. Citizens Advice gives the same advice independently: keep the deposit to 25% at most, pay in stages at milestones, get receipts and pay by card rather than cash. Our guide to paying for a conservatory roof covers deposits, stage payments and finance.
What happens if your installer goes out of business?
The Safestyle administration in October 2023 shows how the protections divide. Customers who had paid cash deposits were told the money would not be repaid, and card payers were told to claim under Section 75. FENSA said completed, registered installations kept their insurance-backed guarantee, but that it could not help with contracts or payments.
Administrators later agreed a deal for Anglian to fulfil orders.
The lesson is that an IBG protects the guarantee after installation, not money paid before it. When a Hull window and conservatory firm entered liquidation in 2024, customer payments became unsecured claims that were unlikely to be repaid. Section 75 applies to credit card purchases of a single item costing over £100 and up to £30,000, and Citizens Advice says it applies even if only the deposit went on the card.
Are conservatory roofs covered by insurance?
Sudden damage, such as a storm, is normally covered by buildings insurance, but the Association of British Insurers says wear and tear and poor maintenance are not. So a roof that leaks because its seals or sheets have aged is usually your cost. Tell your insurer about a new roof, as unreported changes can affect your cover.
When storm claims are disputed, the Financial Ombudsman Service asks whether there were storm conditions on or around the date, whether the damage is consistent with a storm, and whether the storm was the main cause. Claims can fail where the roof was already in poor repair. Buildings cover should reflect the full rebuilding cost, so a solid roof conversion may change your sum insured. Our conservatory roof insurance guide goes into claims in more detail.
Your rights, guarantee or not
A guarantee adds to your legal rights; it does not replace them. Under the Consumer Rights Act 2015:
- The installer must carry out the work with reasonable care and skill.
- Anything the installer told you about the work that you relied on becomes part of the contract.
- Goods installed incorrectly by the trader do not conform to the contract.
- If the work falls short, you can ask for it to be done again at the trader’s expense, within a reasonable time. Which? says that if that is impossible, you may be entitled to a price reduction of up to 100%.
Raise any complaint with the installer first. If it belongs to a scheme such as DGCOS or the Glass and Glazing Federation, you can then use the scheme’s complaints or dispute service. DGCOS’s ombudsman handles claims under £10,000 after the member’s final response or 12 weeks. The Citizens Advice consumer helpline is 0808 223 1133.
Get these in writing before you sign
When you get quotes, ask each installer for the following, and compare them side by side as part of comparing quotes like for like:
- The name of the product guarantee, who issues it and what it excludes.
- The length of the workmanship guarantee and whether it is insurance-backed, with the insurer’s name and the IBG’s own length.
- The deposit amount, whether it is protected, by whom and for how long.
- What maintenance the guarantees require, and whether they transfer if you sell.
- The trade body or scheme the installer belongs to. Check membership with the scheme directly: displaying a trust mark without authorisation is banned under the Digital Markets, Competition and Consumers Act 2024.
Keep every document with your building control completion certificate. You will need them together if you sell the house.
Questions people ask
Can I transfer my conservatory roof guarantee when I sell?
It depends on the terms. ExpertSure's review says the insurance-backed guarantee on a Guardian roof transfers on sale at no fee, but terms differ between manufacturers, installers and insurers. Check the transfer conditions in your documents and pass the paperwork to the buyer.
Is it safer to pay a conservatory roof deposit by credit card?
Yes. Citizens Advice explains that Section 75 of the Consumer Credit Act makes the card provider jointly liable with the trader when an item costs more than £100 and no more than £30,000, even if only part of the cost went on the card. Debit card payments rely on chargeback instead, which only recovers what was paid on that card.
What is DGCOS?
The Double Glazing and Conservatory Ombudsman Scheme is a private company, funded by member installers, that offers deposit protection, insurance-backed guarantees, mediation and an independent ombudsman. The ombudsman's decisions bind the member but not you, and it is not a statutory ombudsman. Check an installer's membership with DGCOS directly rather than trusting a logo.
Does a FENSA certificate cover a new solid roof?
Not by itself. FENSA is a competent person scheme for replacement windows and doors, and none of the government-listed schemes appears to cover converting a glazed conservatory roof to a solid one. A solid roof needs its own building regulations approval, so ask for the completion certificate as well as any FENSA certificate for new windows.
How long do I have to claim for poor workmanship on a conservatory roof?
Which? says you have up to six years to take a claim to the small claims court in England, Wales and Northern Ireland, and five years in Scotland. That applies whether or not the installer's guarantee has run out.
Sources
- Which?: Conservatories, common pitfalls
- TrustMark: Consumer protection
- DGCOS: Protection
- DGCOS: Ombudsman
- HomePro
- QANW
- Consumer Protection Association
- Guardian Building Systems: Consumer promise
- Ultraframe: LivinRoof product page
- Eurocell: Equinox
- SupaLite: Tiled roof
- ExpertSure: Guardian Warm Roof review 2026
- Warmer Roof: Tiled roof system
- Comfy Conservatories
- Leka: The Leka system
- FENSA: Safestyle FAQs for homeowners
- Double Glazing Blogger: Safestyle appoints administrators
- Business Sale: Window and conservatory manufacturer enters liquidation (Colfax)
- Wikipedia: Everest Home Improvement
- Bryant & Cairns: Aluminium insulated roof panels, the pitfalls
- Citizens Advice: Getting your money back if you paid by card
- Consumer Rights Act 2015, section 49
- Which?: Consumer Rights Act
- ABI: Home insurance
- Financial Ombudsman Service: Storm damage
Written by the Conservatory Roof Guide team
We research every figure from named sources: manufacturers' data, Met Office, HM Land Registry, LABC and published UK price guides. How we compare.
Reviewed by Zaib Khan
Founder of Conservatory Roof Guide. His team has handled 9,000+ conservatory roof quote requests from UK homeowners.